



The active public offer could deepen Nigeria’s capital market and demonstrate confidence in a major industrial asset. But even if it is oversubscribed, its outcome should not be treated as conclusive evidence of the health of the wider economy.

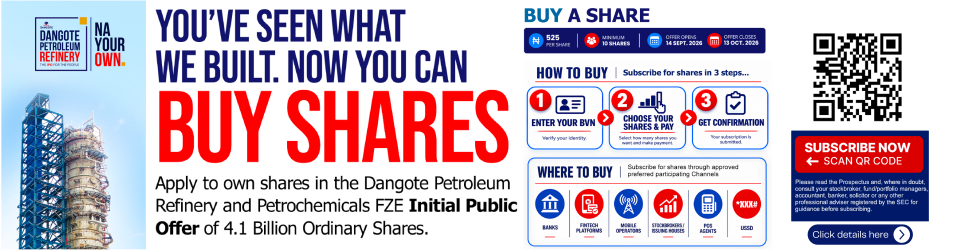
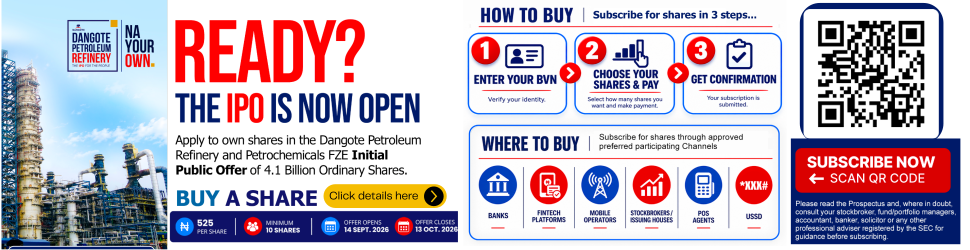
Few corporate events in Nigeria have generated as much anticipation as the initial public offering of Dangote Petroleum Refinery and Petrochemicals FZE, which opened on 14 September. The company is offering 4.1 billion ordinary shares at ₦525 per share, with a minimum subscription of 10 shares costing ₦5,250. The offer is expected to raise approximately ₦2.15 trillion if fully subscribed and is scheduled to close on 13 October. The shares are expected to be listed on the Nigerian Exchange in November, subject to the completion of the offer, allotment and applicable approvals.

|

|
The offer has drawn a great deal of public attention. The refinery represents an interesting national story involving industrial ambition, a decreased reliance on imported petroleum products, and the possibility of transforming Nigeria’s energy sector. Since the minimum required amount is fairly accessible at ₦5,250, the offer has also been structured to promote participation from both retail and institutional investors.
It would therefore not be surprising if the IPO closes oversubscribed. After the offer, attention will turn to the amount raised, the level of oversubscription, the number of applicants, retail and institutional allocations, foreign participation and the share price after listing. Commentators may present strong demand as evidence of a robust economy, a deepening capital market and renewed investor confidence.
|
|
|
|---|
Those conclusions would require caution. Statistical aggregates are valuable, but they do not reveal everything that matters. The gaps behind the headline figures may be especially important when assessing what the IPO says about Nigeria’s economy and the financial circumstances of individual investors.
Demand for the shares is likely to come from many sources. Some investors may be motivated by national pride or confidence in the Dangote brand. Others may follow the crowd, subscribing because they expect strong demand and an increase in the share price after listing. Pension funds, asset managers and insurance companies may participate because the Nigerian market offers relatively few large, liquid assets. Foreign and diaspora investors may also subscribe, while traders and intermediaries may seek shares primarily for resale after listing.

Some subscriptions may be financed from accumulated savings, while others may come from loans, asset sales or money originally intended for household and business needs. Investors may borrow from banks, cooperatives, relatives or digital lenders. Others may sell land, vehicles, jewellery, existing shares, digital assets or business inventory. Funds set aside for rent, school fees, healthcare or working capital may also be redirected towards the offer.

Stay Ahead with Premium Times
Follow us on Google News and never miss breaking stories, investigations, and in-depth reporting.
 Add as a preferred source on Google
As with any financial transaction of this scale, regulators, issuing houses, receiving agents and financial institutions must enforce rigorous customer-identification, source-of-funds and anti-money-laundering requirements. The concern is not that an IPO necessarily legitimises illicit funds, but that an offer of exceptional size requires equally strong financial controls.
These varied funding sources could contribute to oversubscription. That is why the final outcome of the IPO, considered in isolation, would be an unreliable measure of Nigeria’s economic health.
Oversubscription Is a Limited Signal
Oversubscription, by itself, is a weak economic indicator. It can coexist with severe economic distress. In an environment where inflation is eroding savings, the naira is unstable, property is difficult to sell, and conventional savings instruments provide inadequate protection against rising prices, investors may rush towards any credible asset that appears capable of preserving value.
Such demand may not demonstrate widespread prosperity. It may instead reveal a shortage of attractive investment opportunities.
A heavily subscribed IPO could also reflect the concentration of liquidity in relatively few hands while much of the population struggles with falling purchasing power. It could represent speculative demand rather than long-term confidence. It might demonstrate enthusiasm for a particular company without indicating confidence in the economy as a whole.
The offer’s valuation is also central to interpreting demand. Investors are responding not only to the company’s reputation but also to the price of ₦525 per share, the minimum subscription, allocation rules, financial disclosures, expected returns and prevailing market conditions. A compelling valuation could produce substantial oversubscription even in a weak economy. An excessive valuation could produce a disappointing result even if the underlying business and broader economy were improving.
Headline subscription figures will also leave several important questions unanswered. They will not necessarily show:
- whether subscriptions were financed from accumulated savings or borrowed funds;
- whether demand came from millions of small investors or a relatively small number of wealthy individuals and institutions;
- whether investors intend to hold their shares for the long term or sell them soon after listing;
- whether foreign participation represents patient capital or short-term portfolio flows;
- whether banks financed share purchases at the expense of lending to productive businesses; or
- whether households diverted money from education, healthcare, housing and other essential needs.
Gross applications may not be the same as funded and settled subscriptions. Nor would success during the offer guarantee strong performance after listing. An IPO can be oversubscribed and still trade below its offer price if its valuation proves unrealistic, market conditions change, or early investors rush to sell.
These are not minor distinctions. They separate an economy supported by productive savings and long-term investment from one experiencing another episode of speculative excitement.
The IPO Is Important, but Its Meaning Depends on the Details
The limitations of oversubscription do not make the IPO unimportant. The offer is already a landmark for Nigeria’s capital market. It gives individual and institutional investors an opportunity to acquire an interest in a strategically important industrial enterprise. A successful conclusion could broaden share ownership, attract long-term capital and increase the visibility of the Nigerian Exchange.
The offer could also strengthen corporate transparency and governance. As a publicly traded company, the refinery would be expected to meet continuing disclosure requirements and face greater scrutiny from shareholders, regulators, analysts and the market.
The significance of the transaction will nevertheless depend on its structure and aftermath. It is important to distinguish capital raised for the company from proceeds accruing to any selling shareholders. The identity of the legal issuer, the assets and obligations included in the listed entity, the intended use of the proceeds and the rights attached to the shares all affect how the transaction should be interpreted.
If new capital is being raised for expansion, its eventual economic value will depend on how efficiently it is deployed. Raising ₦2.15 trillion would be impressive, but the more important questions are whether the funds increase productive capacity, improve operational performance and generate sustainable returns.
What the IPO Figures Should Reveal
A meaningful assessment should go beyond the amount raised and the oversubscription ratio. Investors, regulators and economic commentators should examine the composition, source and quality of demand.
Useful information would include:
- the number and average size of retail subscriptions;
- the proportion of the offer allotted to retail and institutional investors;
- the concentration of shares among the largest subscribers;
- the allocation between domestic and foreign investors;
- the extent to which subscriptions were financed with credit;
- the valuation relative to earnings, cash flow, assets and comparable companies;
- the precise use of the proceeds;
- trading liquidity and price stability after listing;
- the proportion of investors retaining their shares over time; and
- the refinery’s subsequent operating performance and disclosure standards.
These details would not provide a perfect picture, but they would make it easier to distinguish broad participation from concentrated wealth and durable investment from short-term speculation.
Retail participation deserves particular attention. The minimum subscription of 10 shares makes the offer accessible in principle, but affordability does not necessarily guarantee broad ownership. The eventual distribution of allotments will reveal whether the offer genuinely widened participation or remained concentrated among large investors.
Better Measures of Economic Improvement
A reliable assessment of Nigeria’s economy must draw on a much wider range of evidence. Real wages and employment matter because they show whether households are gaining purchasing power and access to livelihoods. Inflation, particularly food and energy inflation, matters because it directly affects living standards.
Manufacturing capacity utilisation, electricity supply and the cost of doing business indicate whether companies can produce competitively. Access to affordable credit shows whether small and medium-sized enterprises can invest, expand and employ more people. Exchange-rate stability, foreign reserves and export diversification reveal whether the external sector is becoming more resilient.
Productive foreign direct investment is generally more informative about long-term confidence than short-term portfolio flows into a single prominent asset. Capital formation, domestic savings, broad-based tax revenue, poverty reduction, security and human-development outcomes also provide a better picture of whether economic progress is reaching the wider population.
These indicators speak to the lived experience of millions of Nigerians. A single IPO, regardless of its size or prominence, cannot replace them.
When the IPO Could Be a Positive Signal
The final outcome could still form part of a positive economic story. If millions of ordinary Nigerians participate using genuine disposable savings; if pension funds, insurers and asset managers invest long-term domestic capital; if foreign investors provide patient funding; and if the listing strengthens transparency and corporate governance, the transaction could indicate progress in important areas.
Its economic significance would be greater if the capital financed productive expansion, the refinery operated efficiently, and its activities generated wider benefits through employment, reliable petroleum-product supply, stronger domestic value chains, lower logistics costs and sustainable returns for shareholders.
Even under those circumstances, the IPO would be one positive indicator rather than a verdict on the entire economy.
If, on the other hand, much of the demand is driven by excessive borrowing, distressed asset sales, depleted household savings or expectations of a quick post-listing profit, oversubscription would say less about economic strength. It might instead reflect a mixture of scarce investment opportunities, concentrated liquidity, inequality, financial anxiety and hope.
The Dangote Refinery IPO is a landmark event. Its scale, relatively low minimum subscription and expected addition of a major industrial enterprise to the Nigerian Exchange make it significant for the country’s capital market. If fully subscribed, it will mobilise approximately ₦2.15 trillion and could become an important test of Nigeria’s capacity to fund large domestic enterprises through public markets.
But it should not be treated as a national economic X-ray. Its real meaning will depend on who subscribes, how subscriptions are financed, how shares are allocated, how the proceeds are used and how the company performs after listing.
The true test will come after the offer closes and the initial excitement subsides: whether the refinery delivers, whether the capital market becomes deeper and more transparent, whether capital flows towards productive sectors and whether ordinary Nigerians experience tangible benefits. Until those results become visible, strong subscription demand may reveal more about Nigeria’s hunger for credible investment opportunities than about the strength of its economy.
Bolutife Oluwadele is a public policy scholar, author, and governance commentator based in Canada. He is also a chartered accountant and certified fraud examiner. Email: [email protected]
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.

More News